


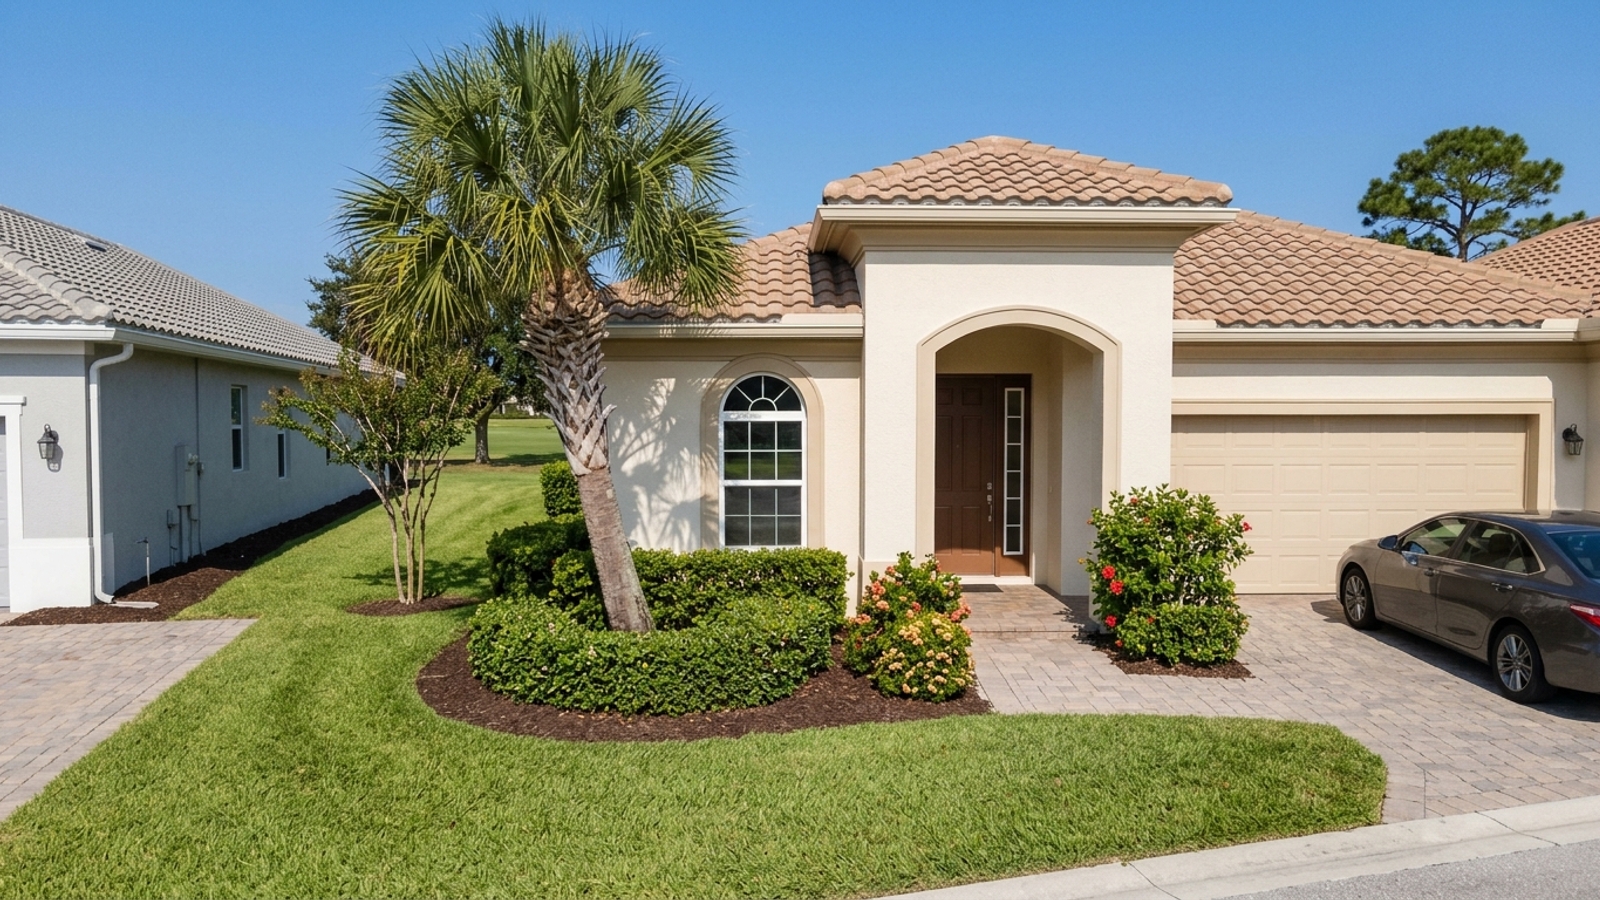
PGA Village is two markets heading into 2027, not one. The headline figures show all homes dropping over the past year, but that number overstates the softness considerably.
The reality comes down to property type. Single-family homes held up well, while townhouse prices rose during the same period. The mix of homes sold shifted, and that shift is creating distinct opportunities depending on what you want to buy or sell.
Key Takeaway
If you are buying in PGA Village, single-family homes give you the most room to negotiate right now. They have 5.3 months of supply, which is enough inventory that sellers are competing for your offer. Townhouses are the exception: listings are scarce and prices are still rising, so expect to pay close to asking there.
Who This Guide Is For
Anyone weighing a PGA Village purchase or sale now, or deciding between a single-family home and a townhouse based on budget and timeline.
PGA Village Housing Market Outlook for the Next 12 Months
The overall PGA Village market saw a notable drop in median sale prices over the 90 days ending September 30, 2026. Neither property type fell that far on its own, though. Single-family home prices dipped slightly, and townhouse prices climbed 4.4% (based on 35 sales). What that tells you is that the mix of homes sold shifted toward lower-priced properties, rather than values plummeting across the board.
The overall market sits at 5 months of supply. Months' supply measures how long it would take to sell the current inventory at the current sales pace, and a 6-month supply is generally considered a balanced market, according to NAR. PGA Village is hovering just below that mark, which keeps conditions relatively stable.
Your strategy for the coming year depends entirely on what you are shopping for: a house or a townhouse. You can review the broader PGA Village housing market page to compare the price history, but the daily reality on the ground is split by property type.
Single-Family Homes vs. Townhouses in PGA Village
Most of what's for sale in PGA Village is single-family housing. That volume puts buyers in a position to negotiate on price, request repairs, or ask for closing credits. The softening here is gradual, meaning you have room to maneuver without the market looking distressed.
Townhouses are a completely different environment, defined by scarcity. Patient sellers get their price, and buyers have little to choose from. When deciding between the two, you are choosing between negotiating power and a lower entry price.
Single-Family Homes
There were 520 single-family homes for sale over the 90 days ending September 30, 2026, roughly 20 houses available for every townhouse listed. The median sale price sits at $459,884, giving buyers a clear anchor for their budget.
The downside is that the same inventory helping you negotiate means prices could keep drifting. If you buy now and need to resell within a couple of years, you may find yourself competing with a deep pool of similar listings.
Townhouses
Only 27 townhouses were on the market during that same 90-day window. They're the slowest PGA Village homes to sell, at a median of 143 days based on 35 sales, yet they're the only type whose prices went up. A slow pace with thin supply means patient sellers eventually get their asking price.
The lower entry price is the main draw, but ask whether a given townhouse is held as a condominium, since that affects insurance, financing, and association rules. What you give up is choice: you may wait months for the right floor plan to come up, and you'll have little room to haggle when it does.
What Could Change the Forecast
Mortgage rates will dictate how quickly the current inventory moves. As of October 29, 2026, the 30-year fixed-rate mortgage averaged 7.24%, down from 7.32% the prior week, but up from 6.17% a year earlier. Lower rates could absorb single-family inventory and firm up prices; flat rates point to more of the same.
The published outlook suggests rates will stay high. In its October 2026 forecast, Fannie Mae projected the average 30-year fixed mortgage rate at 7.4% for Q4 2026 and 7.5% throughout all of 2027, a sharp increase from its prior estimates. The MBA's baseline forecast also calls for 30-year mortgage rates to remain above 7% through 2027.
Beyond rates, local carrying costs and new construction compete with resale homes. You can check the new construction page to see what builders are offering. Always get a homeowners insurance quote before going under contract, and check the property tax and HOA fees pages to estimate your total monthly obligation.
Is It a Buyer's or Seller's Market in PGA Village?
Single-family homes lean toward buyers, with plenty of options and flexible sellers. Townhouses lean toward sellers, rewarding those who can afford to wait for the right buyer. Knowing which side of that line your property falls on dictates how you handle negotiations.
Advice for Buyers
A typical PGA Village house closes about 2.5% under its asking price. On a hypothetical home listed at $470,000, a 97.5% sale-to-list ratio implies a final price around $458,250, roughly $11,750 under asking.
You can use the high inventory to negotiate on houses, while expecting to pay closer to asking for townhouses. Ask the listing agent for the home's price-reduction history, and confirm current dues with the HOA and CDD.
The catch is that averages conceal the spread. Well-priced homes on popular courses or lots still draw near-full offers, so a lowball on the wrong house can lose it. Factor in buyer closing costs when making your offer.
Advice for Sellers
A typical single-family sale takes a median of 108 days, so budget your mortgage, HOA, insurance, and utility payments for at least three months. Pricing high and hoping for a bidding war rarely works here: only about one in eleven PGA Village houses sold above asking (9.2%). Townhouse sellers can price closer to market with more confidence.
Review pricing strategies and expectations for how long to sell before listing. A no-pressure pricing review of recent comps is worth doing before you set a number. An overpriced home often ends up selling for less after price cuts than it would have at the right price on day one.
How to Use This Forecast for Your Decision
Your next step depends on your specific timeline and goals. Start by identifying whether you are shopping for a house or a townhouse, because the two are moving in opposite directions.
If you need to sell before you buy, read the advice for sellers first. A typical single-family sale takes more than three months and should set your timeline. Consider whether a drop in mortgage rates would change what you can afford, and check the affordability guide. If you expect to move again in under five years, the softening single-family prices matter more to you than they would to a long-term owner.
Confirm current market figures before acting. The statistics on this page reflect a 90-day snapshot ending September 30, 2026, and do not constitute financial advice.
At a Glance
- Median sale price: all homes $439,866 (down 6.1% YoY); single-family $459,884 (down 2.9% YoY); townhouse $346,500 (up 4.4% YoY, based on 35 sales). 90 days ending 2026-09-30.
- Homes sold: all homes 338; single-family 299; townhouse 35. 90 days ending 2026-09-30.
- Median days on market: all homes 109; single-family 108; townhouse 143. 90 days ending 2026-09-30.
- Sale-to-list price: all homes 97.6%; single-family 97.5%; townhouse 98.3%. 90 days ending 2026-09-30.
- Share sold above list price: all homes 8.8%; single-family 9.2%; townhouse 5.9%. 90 days ending 2026-09-30.
- Months of supply: all homes 5; single-family 5.3; townhouse 2.3. 90 days ending 2026-09-30.
- Homes for sale (inventory): all homes 547; single-family 520; townhouse 27. 90 days ending 2026-09-30.
- Median price per square foot: all homes $217; single-family $223; townhouse $206. 90 days ending 2026-09-30.
- Condos: fewer than 10 sales in the window, so no figures are reported.
PGA Village Housing Market Forecast FAQs
Is the PGA Village Housing Market Predicted to Crash?
The current numbers point to a cooling market rather than distressed selling. Over the 90 days ending September 30, 2026, homes still sold at 97.6% of their list price, and 8.8% sold above asking. The overall market has 5 months of supply, which is close to the 6-month benchmark that NAR considers a balanced market.
Where Will PGA Village Home Prices Be in 5 Years?
No reliable five-year forecast exists for a single community like PGA Village. Check the FHFA house price index for the Port St. Lucie metro to see long-term changes in the broader area. A horizon of five or more years reduces your exposure to short-term market softening.
Is It Better to Buy a House in PGA Village Now or Wait Until 2027?
Waiting for lower rates may not pay off, as Fannie Mae projects the average 30-year fixed mortgage rate at 7.5% throughout all of 2027, up from their prior forecasts. The MBA also expects rates to remain above 7% through 2027. Compare the payment at today's rate against the forecast rate using a lender's quote; waiting could also mean facing more competition for today's inventory.
Are Home Prices Rising in Florida?
For September 2026, the statewide median sales price for single-family existing homes was $415,000, up 1.2% year-over-year. By contrast, PGA Village saw single-family prices drop slightly, while townhouse prices rose. Check the "At a glance" list for the specific local breakdowns.
What Is the 3-3-3 Rule in Real Estate?
There is no single official definition for the 3-3-3 rule; it's an informal guideline used variably by industry sources. Common versions suggest buying a home no more than three times your annual income, putting 3% down, and keeping housing costs under 30% of gross income, or keeping three months of savings and comparing three homes. When budgeting for a PGA Village purchase, remember to include HOA fees and insurance, and review our affordability guide.
What Is the Monthly Mortgage Payment for a $400,000 House in PGA Village?
For illustration only: at a 7.24% rate with a 20% down payment, the principal and interest on a $400,000 house would be roughly $2,176 a month. Add the specific PGA Village costs on top of that, including property taxes, insurance, HOA dues, and CDD fees where applicable. Look up the property's current assessed value on the St. Lucie County Property Appraiser site and get an insurance quote to find your exact payment.
Are Condos Selling in PGA Village?
Condos had fewer than 10 sales in the 90 days ending September 30, 2026, so no reliable figures are reported for them. Under Florida Statute 553.899, condominium buildings three or more stories must undergo a milestone structural inspection when they turn 30, and complete a Structural Integrity Reserve Study. Ask the association for its reserve study and inspection status, and check the condos page for more details.
How Much Does Homeowners Insurance Cost in PGA Village?
Check the Florida Office of Insurance Regulation for the average homeowners insurance premium in St. Lucie County. Actual premiums depend on the roof's age, wind mitigation features, and the specific flood zone. Get an exact quote before going under contract.